Jeffrey Epstein &
Financial Crimes Enforcement Network (FinCEN)
Bureau, US Department of the Treasury
Key Facts
$150 million fine for failing to monitor Epstein's transactions properly
Regulatory Penalty Against Deutsche Bank
NYDFS Consent Order (2020)
Suspicious Activity Reports (SARs) filed under the Bank Secrecy Act
Primary AML Reporting Tool
FinCEN Files (2020)
JPMorgan Chase (late 1990s–2013) and Deutsche Bank (2013–2018)
Core Institutional Banks
USVI v. JPMorgan Court Filings
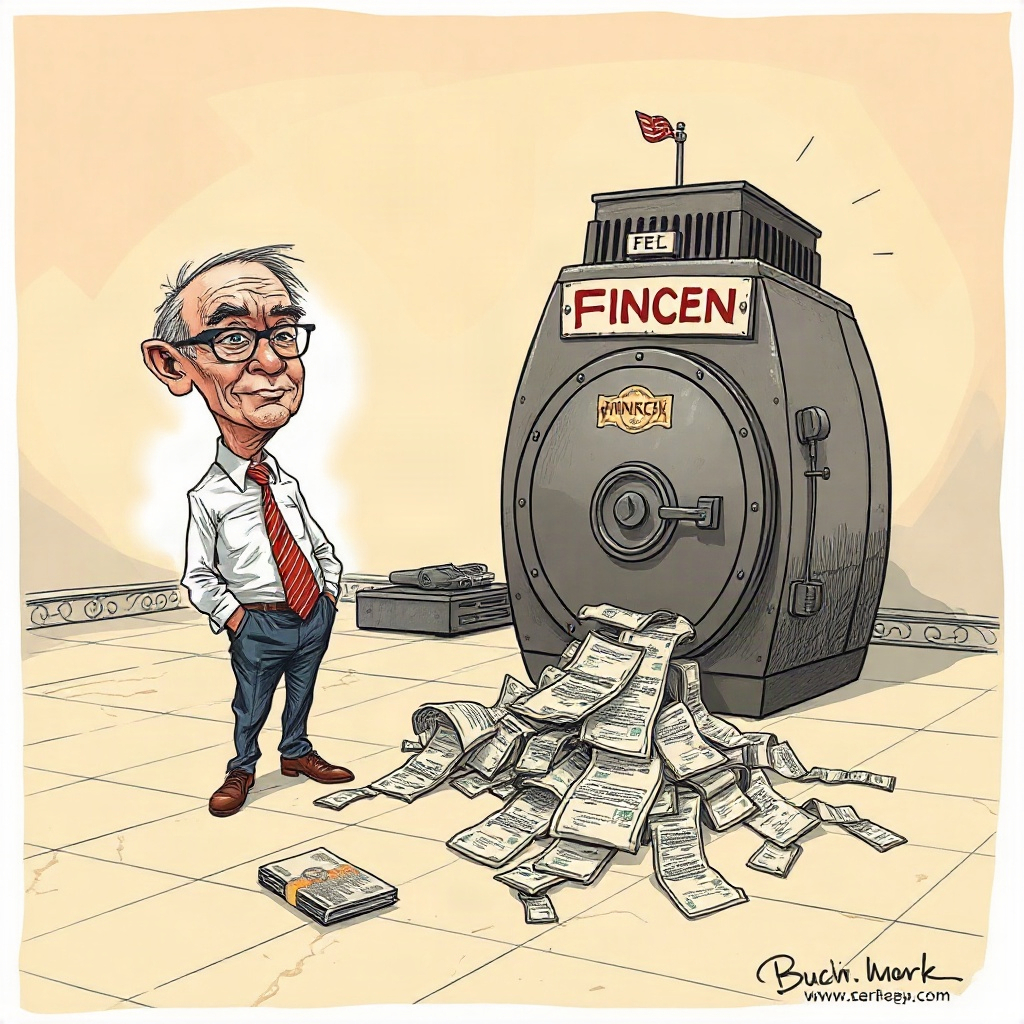
Financial Crimes Enforcement Network (FinCEN) · Bureau, US Department of the Treasury
Operating as a bureau of the United States Department of the Treasury, the Financial Crimes Enforcement Network (FinCEN) is tasked with safeguarding the national financial system from illicit use, combating money laundering, and promoting national security through the collection and analysis of financial intelligence. Central to its mission is the administration of the Bank Secrecy Act of 1970, which requires financial institutions to file Currency Transaction Reports for large cash transactions and Suspicious Activity Reports (SARs) whenever transactions appear irregular, lack an apparent lawful purpose, or resemble money laundering. While FinCEN does not maintain an independent prosecutorial arm, its repositories serve as the principal intelligence reservoir for federal law enforcement agencies seeking to dismantle illicit financial networks. In the aftermath of Jeffrey Epstein's 2019 arrest and subsequent death, the federal clearinghouse of SARs emerged as ground zero for understanding how the disgraced financier moved hundreds of millions of dollars unimpeded through global banking institutions.
For more than two decades, Epstein utilized marquee global banks—most prominently JPMorgan Chase until 2013, followed by Deutsche Bank between 2013 and 2018—to execute complex financial transfers across a labyrinth of corporate and trust entities. His transactions routinely involved characteristics that regulatory guidelines define as classic red flags: massive physical cash withdrawals, recurring wire transfers to young women in Eastern Europe and South America, multi-million-dollar settlements with non-disclosure clauses, and frequent internal transfers between opaque holding companies based in the U.S. Virgin Islands. Bank compliance departments were legally mandated to capture these anomalous patterns and route detailed narratives to FinCEN, yet Epstein maintained access to private wealth management services, private jets, and offshore entities with virtually no administrative interruption by federal authorities.
The mechanics of the Bank Secrecy Act created a systemic paradox that Epstein’s banking partners exploited. Under federal law, filing a SAR grants a financial institution a degree of regulatory insulation, demonstrating that the compliance department identified and logged suspicious activity. However, banks are generally not required to terminate a client relationship upon filing a SAR, and federal law strictly prohibits institutions from disclosing the existence of a SAR to the client or the public. Consequently, institutions could continually service Epstein’s highly lucrative accounts, collect advisory fees, and satisfy regulatory check-boxes by privately dispatching SARs to FinCEN's central database in Merrifield, Virginia, where millions of such filings accumulated every year with limited investigative follow-up.
Related articles
Jeffrey Epstein and Central Intelligence Agency (CIA)
An investigative review of alleged ties between Jeffrey Epstein and the CIA, examining FOIA filings, Acosta's remarks, and official calendar records.
Read article →
Jeffrey Epstein and Federal Bureau of Investigation (FBI)
An investigative analysis of Jeffrey Epstein's decades-long history with the FBI, from the 2006 Palm Beach probe to the 2019 Manhattan raid and FOIA files.
Read article →
Jeffrey Epstein and Secret Intelligence Service (MI6)
Investigative analysis of Jeffrey Epstein's alleged links to Britain's Secret Intelligence Service (MI6), Ghislaine Maxwell, and elite UK networks.
Read article →
Jeffrey Epstein and Directorate-General for External Security (DGSE)
Investigating allegations and public records regarding Jeffrey Epstein, his Paris operations, and France's foreign intelligence agency, the DGSE.
Read article →